Borrowing Against the Collection: Art as Collateral
A painting that cannot be sold quickly can still raise money. Art secured lending lets collectors keep the work on the wall and put its value to use.
Premieur Oct 29, 2026 2 min read
Follow Premieur
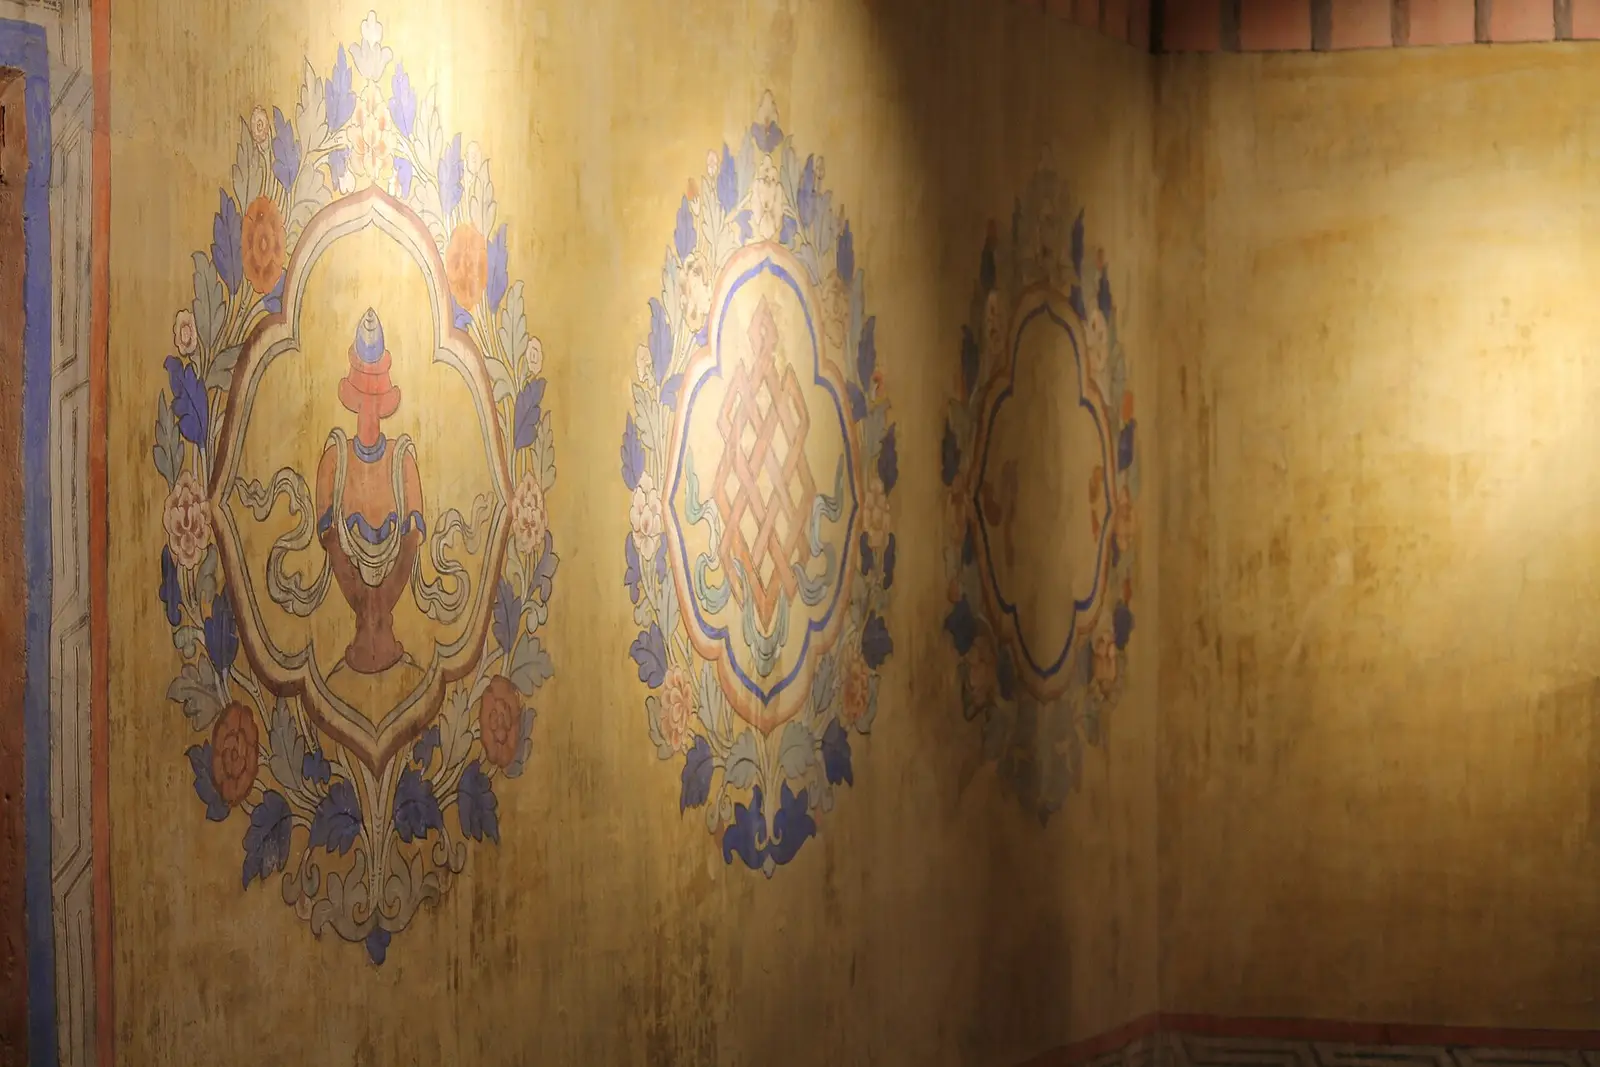
Wall paintings in a museum gallery. Photo: RPSkokie, Wikimedia Commons, CC BY 3.0
The great weakness of art as an asset is that turning it into cash is slow and expensive. A growing number of collectors have found a way around part of that problem: rather than selling, they borrow against the collection, keeping the work while freeing up some of its value.
How the loans work
Private banks, specialist lenders and some auction houses will lend against art, typically advancing a portion of the appraised value rather than the full amount, often around half or less. The loan is secured on the works, which usually stay with the owner, insured and sometimes subject to conditions on where they can hang or travel. Terms depend heavily on the quality of the art, the strength of its market and the borrower's wider relationship with the lender.
Why collectors use them
The appeal is liquidity without a sale. A collector can fund a business opportunity, cover a tax bill or buy another work without triggering the fees and taxes of selling, and without parting with a piece they would rather keep. For owners whose wealth is concentrated in illiquid assets, a line of credit against the collection can be the most efficient source of cash available.
Lending against art depends on appraisals in a market where prices are thin and can move sharply. If values fall, a lender may ask for more collateral or repayment, and a forced sale in a weak market is exactly the outcome an art owner most wants to avoid. Title also matters enormously: a lender needs certainty that the borrower owns the work outright, with no competing claims, which is why provenance research is part of every serious loan.
What it means for capital
For someone allocating capital, art secured lending turns a collection from a purely illiquid holding into one that can support the rest of a balance sheet. Used conservatively, with a loan well inside the collection's value, it is a sensible tool. Used aggressively, it adds leverage to the least liquid asset a family owns, and that is a combination that rarely ends well in a downturn.
Comments